Funding desk is open · applications reviewed 7 days
Navigate
HomeAll funding programsIndustriesHow it worksFunding estimatorResources & guidesFAQPartner programAbout TravisContact
Funding programs
Working CapitalLine of CreditSBA 7(a) & 504Term LoansEquipment FinancingInvoice FactoringRevenue-Based AdvanceReal Estate InvestorStartup FundingBusiness Credit
HomeFundingEquipment Financing
Equipment financing

Let the machine pay for itself.

The equipment secures the loan, which makes approval easier than unsecured money and down payments often unnecessary. You keep your cash and your credit lines intact.
Up to $2MFinancing amount
$0 downAvailable options
24–84 moTerm length
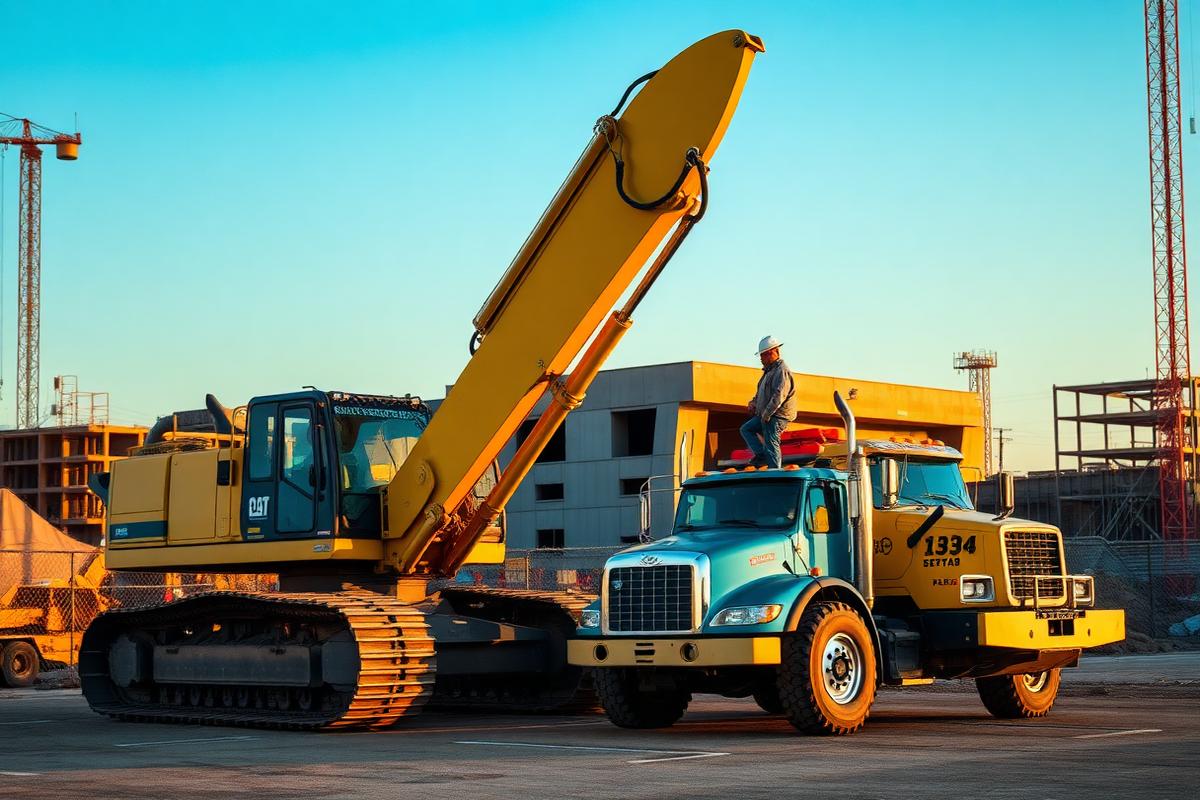
A contractor inspecting a financed excavator and work truck at a job site
Overview

Self-collateralizing capital — the easiest yes in business lending

Because the asset backs the note, an equipment lender is underwriting a machine with a resale market alongside your business. That shifts the risk calculation and opens approvals for files that unsecured lenders decline — thinner credit, shorter history, tighter margins.

We finance both new and used, from dealers or private parties: excavators and skid steers, box trucks and tractors, CNC and press brakes, commercial kitchen lines, medical and dental chairs, HVAC and refrigeration, printing, POS and IT infrastructure. Soft costs — delivery, installation, training, extended warranty — can usually be rolled into the same contract.

  • Up to $2,000,000 per transaction
  • $0 down on many approvals; first-and-last on others
  • New or used, dealer or private-party sale
  • Application-only approvals under $150,000, often same day
  • Section 179 may allow a full first-year deduction — confirm with your CPA
  • Sale-leaseback available to pull cash out of equipment you already own

Asset-secured

Easier approval than unsecured debt.

$0 down

Keep working capital where it is.

App-only

No financials under $150K on most files.

Every figure here is a typical range across our network, not a quote. Real terms come from your file.
Rates & terms

What this program actually looks like.

Amount$5,000 – $2,000,000
Term24 – 84 months
Rate6% – 25% APR by credit and asset class
Down payment$0 to 20%
Structures$1 buyout, 10% PUT, FMV lease, EFA
Time to fundingSame day to 5 business days
CollateralThe financed equipment
Soft costsDelivery, install and training usually financeable

Ranges reflect typical structures across our lending network. Final terms are set by the funder after underwriting.

Qualifying

What underwriting looks for

  • 6+ months in business (startup programs available)
  • 550+ personal FICO for most asset classes
  • $10,000+ monthly revenue
  • Equipment invoice or dealer quote
  • Private-party sales may require an inspection or appraisal

Documents to have ready

  • One-page application
  • Equipment quote or invoice
  • 3 months of bank statements
  • Driver's license
  • Financials only above roughly $150,000
Send statements as PDFs straight from online banking. Screenshots and scans slow underwriting by days.
The process

From first call to funded

  • 01

    Quote

    Send the invoice or dealer quote and the pre-qualification.

  • 02

    Approve

    Application-only decisions under $150K often come back the same day.

  • 03

    Document

    Sign the finance agreement; we coordinate directly with your vendor.

  • 04

    Deliver

    The vendor is paid and the equipment ships. You start on the first payment date.

Right fit

When this is the answer

  • A machine that unlocks a job you can't currently take
  • Replacing equipment before it fails mid-season
  • Adding fleet capacity against signed contracts
  • Pulling cash out of owned equipment via sale-leaseback
  • Anything with a resale market and a service life
Look elsewhere

When it isn't

  • Highly specialized assets with no secondary market
  • Equipment you'll outgrow inside a year
  • Consumables or inventory
  • A purchase you can cover in cash without straining reserves
Questions

Equipment Financing, answered.

Yes. Age and hours affect term length and rate — most funders cap the term so the note doesn't outlive the asset. Private-party purchases are financeable, sometimes with an inspection or appraisal.
A tax provision that can let you deduct the full purchase price of qualifying equipment in the year it's placed in service, rather than depreciating it over years. Limits change annually. We're not tax advisors — confirm the current numbers with your CPA.
Finance with a $1 buyout when you'll keep the asset for its full life. A fair-market-value lease lowers the payment and suits equipment you'll refresh every few years — technology especially. We'll show both structures side by side.
You sell equipment you already own outright to the funder, receive the cash, and lease it back. It converts a paid-off asset into working capital without a new loan on your balance sheet. Useful when you're equipment-rich and cash-tight.
Often yes, because the asset carries much of the risk. Expect a modest down payment and a personal guarantee. This is one of the few real funding doors open in the first year of business.
Also worth a look

Programs that pair well with this

Working Capital

$10K–$2M in 1–3 days for payroll, inventory and opportunity.

View program

SBA 7(a) & 504

Up to $5M at the lowest rates and longest terms available.

View program

Startup Funding

Real options from 3 months in business — not a brush-off.

View program
Ready when you are

Ready to move on equipment financing?

A four-minute application, a soft review, and no impact on your credit. Travis reads every file personally and calls back with real options — usually the same business day.

Talk to Travis directly612-927-2055

Soft review · No obligation · No impact on your credit score

Call now Pre-Qualify